Written Bids
Clear bids your buyer, lender, and 203(k) consultant can read.
1. Send the repair list.2. Get a written bid.3. We do the work.
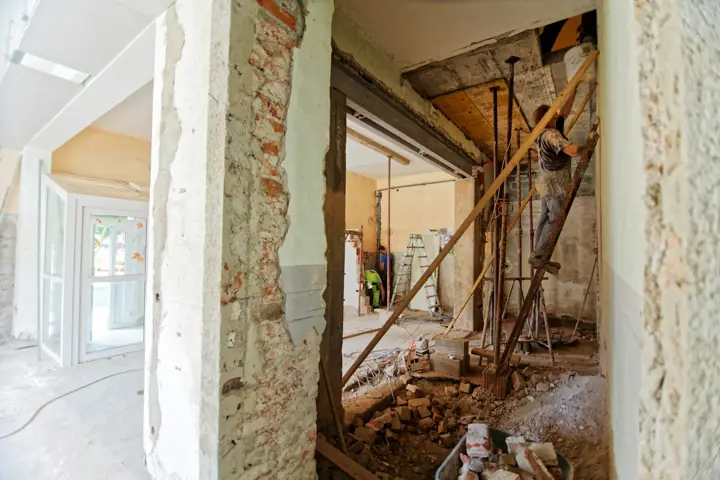
Your buyer found the right home, but the lender or appraiser wants repairs first. Send us the list. We help you keep the deal moving.
Clear bids your buyer, lender, and 203(k) consultant can read.
Each repair is listed out. It matches the lender’s list.
We give the completion and draw papers the loan needs.
Payment comes from the repair escrow or holdback, on the lender’s schedule.
We try to reply the same business day. Deadlines matter.
You get photos when the work is done. Easy to share with your client.
The work is done after closing. It is paid from a repair escrow or holdback.
Smaller repair lists rolled into your buyer’s FHA loan.
Bigger repair loans. We bid the parts we can do.
Escrow holdback repairs on VA and conventional loans.
Important: On 203(k) and holdback jobs, payment goes through escrow or the lender’s draw process. It does not come from the homeowner directly. The work must match the lender-approved scope and bid. Final payment is released after the lender’s inspection. The lender and HUD/FHA set the rules and timelines.
Job size: These jobs get their own written bid. They are not flat-price packages. Our California contractor license is pending. For now, we only take jobs under $1,000 total (labor and materials). For bigger lists, we tell you up front what we can do.
Send the address and the lender, appraiser, or inspection repair list.
We send a clear bid and scope of work for the loan file.
After closing, we do the work and send the draw papers and photos.
Send it today. We reply with a written bid.